Key takeaways
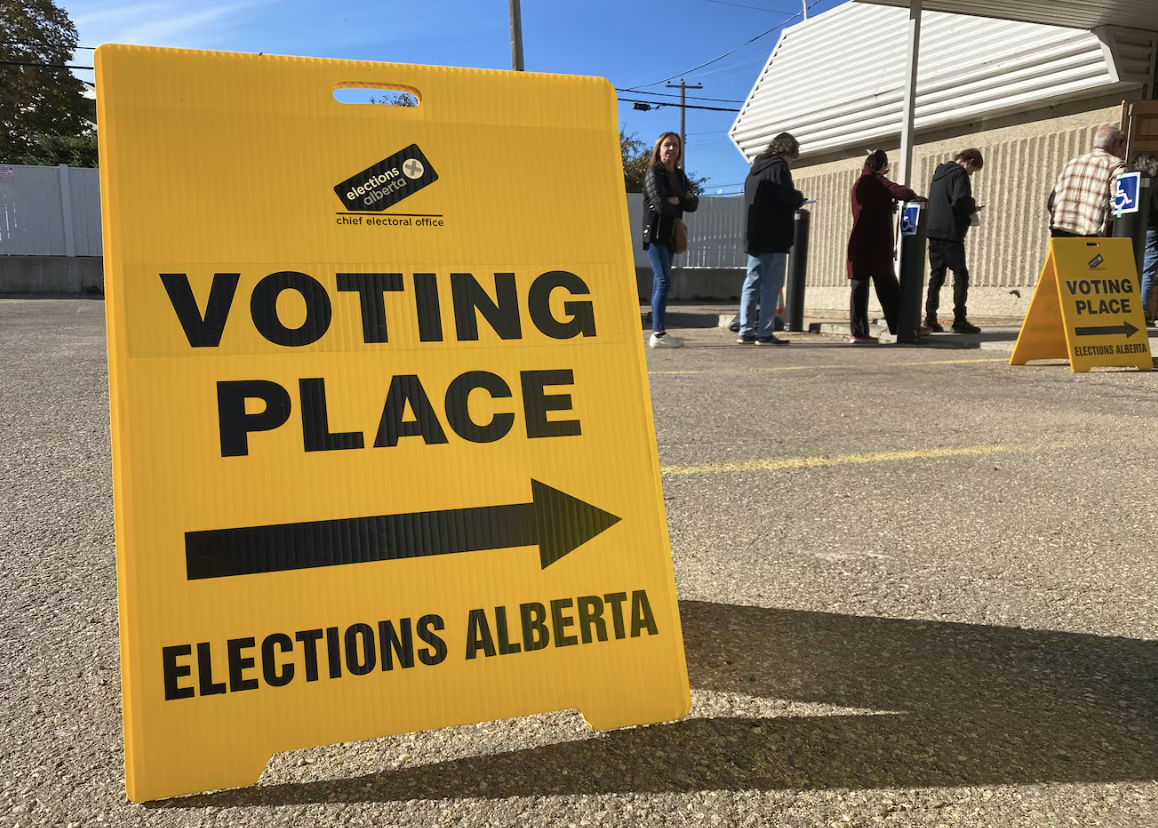
- Alberta’s nonbinding referendum rejected beginning a legal process toward a future separation vote, with early results showing 75.7% voting to remain.
- The Canadian dollar reached a four-week high on October 20, but Reuters cited several factors beyond the vote, including the Canada–U.S. yield gap and expectations for the Bank of Canada.
- The Bank of Canada is scheduled to release its rate decision and Monetary Policy Report at 9:45 a.m. ET on October 28, 2026; the decision is not yet known.
- Variable-rate mortgages and HELOCs are most directly affected by the Bank’s policy rate, while fixed mortgage rates are not set by the referendum or directly by the overnight rate.
What changed since the referendum result
The new development for mortgage shoppers is not a change in mortgage rules — it is the market reaction after Alberta’s vote and the upcoming Bank of Canada announcement on October 28. Alberta voters rejected beginning a legal process toward a future separation referendum, with early results showing 75.7% voting to remain and 24.3% voting to proceed. The ballot was nonbinding and was not a direct vote on independence.
That vote coincided with a stronger Canadian dollar. On October 20, Reuters reported the loonie was up 0.5% at 1.4045 Canadian dollars per U.S. dollar, or 71.20 U.S. cents, after touching 1.4033 — a four-week high. The Yahoo report cited a smaller 0.36% gain against both the U.S. dollar and euro, which shows how the reported move can vary depending on the comparison and timing used.
Why the loonie moved — and why that does not equal a mortgage forecast
It is tempting to draw a straight line from the referendum result to mortgage rates, but that would be too simple. Reuters also cited a narrowing Canada–U.S. two-year yield gap and increased market expectations of a Bank of Canada rate hike. In other words, the vote may have been part of the market backdrop, but it was not the only factor moving the dollar.
For homeowners and buyers, the key point is that a stronger loonie does not automatically mean your mortgage rate is about to change. Currency moves can reflect shifting investor expectations, but lenders price mortgages using a wider set of inputs. A one-day currency move is not a reliable forecast of where lender rates will land.
October 28 is the date to watch
The Bank of Canada has scheduled its next interest rate announcement and Monetary Policy Report for 9:45 a.m. ET on October 28, 2026. The Bank’s policy-rate page listed the target at 2.25% on September 2, 2026, but the available information does not establish what the Bank will decide on October 28.
- If the Bank raises its policy rate, variable-rate mortgage and HELOC borrowing costs could rise through the prime-rate channel.
- If the Bank holds, that direct policy-rate channel would be unchanged for now.
- Fixed mortgage rates are not set directly by the overnight rate, so borrowers should avoid assuming the referendum or the loonie’s move will automatically change fixed-rate offers.
What borrowers should do now
If you have a variable-rate mortgage, a HELOC, or a renewal coming up, the practical move is to be prepared rather than try to predict the announcement. Know your payment sensitivity, review your renewal window, and compare options based on your actual mortgage structure — not just the latest headline about the dollar or politics.
A Finevo advisor can help you understand how the October 28 decision may affect your specific options, compare mortgage choices across 40+ Canadian lenders, and map out a plan for renewing, buying, refinancing, or managing variable-rate debt with less guesswork.
This article is general information about Canadian mortgages and is not financial advice. Rates, programs, and eligibility are subject to change and to lender and insurer qualification. Figures cited reflect market conditions at the time of writing. Speak with a licensed Finevo advisor for guidance specific to your situation.